Is a 5% Stop Too Tight in Today’s Market?
I got a great comment recently:
“It’s just that -5% is not much in today’s markets. Not enough not to get whipsawed. What’s your view?”
Here’s my answer.
I disagree.
There are still plenty of setups where you can risk 5 percent or less.
If that wasn’t the case, traders like Kristjan Kullamägi wouldn’t be as successful as they are.
Same with Mark Minervini. He won the U.S. Investing Championship in 2021. He’s still finding tight entries in today’s market.
It comes down to tactics and timing.
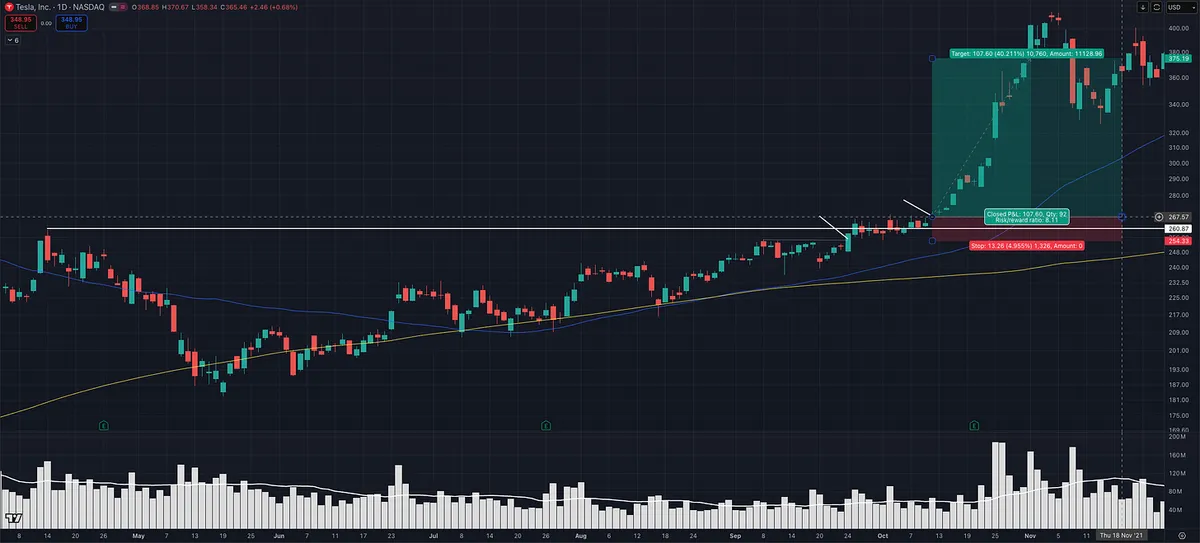
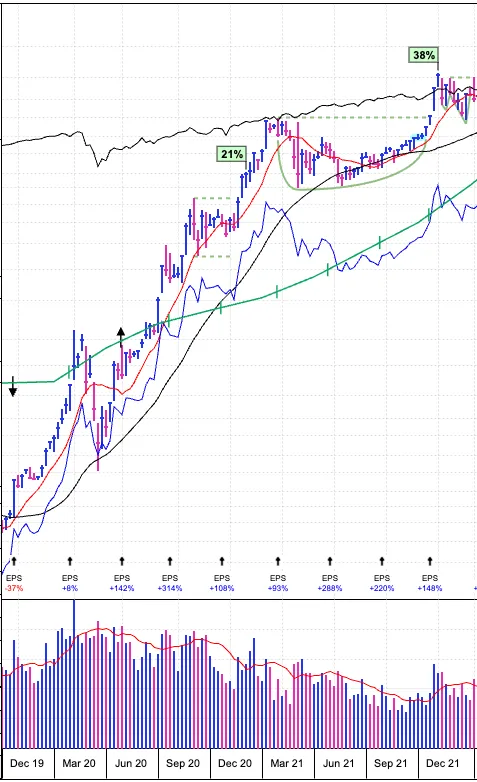
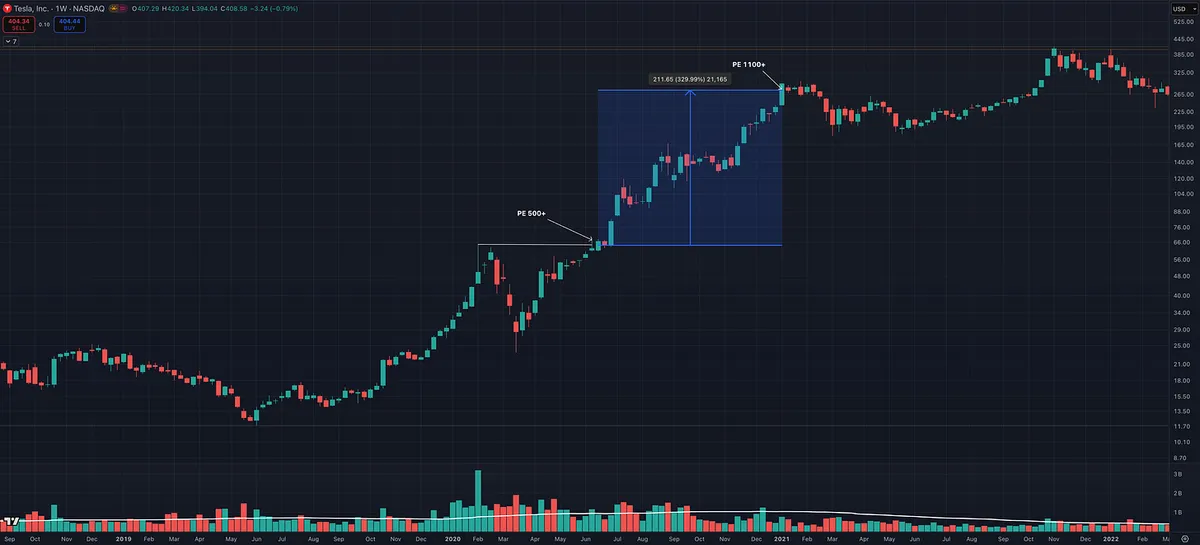
This TSLA example is a good illustration.
On the right side of the base, price was tightening and structure was clean. That created multiple opportunities where risk could be kept at 5 percent or less.
Recently (2025-2026), with many of the big winners already extended in Stage 2 uptrends, it’s a different environment.
If you’re only buying standard breakouts here, then yes, your stop likely needs to be 7 to 10 percent.
But that’s just one way to play it.
A lot of the big winners from 2025 to now in areas like computer data storage and telecom, names like LITE, SNDK, MU, CIEN, WDC, were harder to trade with tight risk using traditional breakout entries.
Their ADR% was higher, and there was less contraction into the pivot, so traders had to adapt.
Pullback entries. Low cheats. Intraday entries like ORB.
Those allow you to define risk much tighter and still participate without getting shaken out.
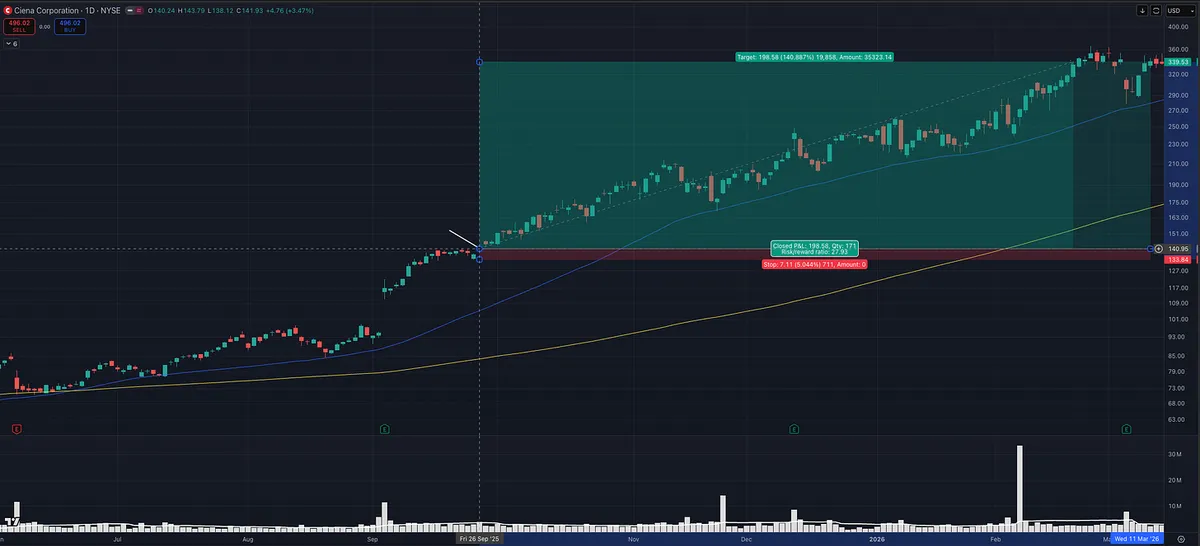
CIEN is another good example.
After an episodic pivot on earnings, price ran, then tightened sideways. That created a clean opportunity to enter with defined, tight risk.
This isn’t about forcing a fixed 5 percent stop on every trade.
It’s about finding entries with proven setups where tight risk actually makes sense.
Timeframe matters. Setup matters. Execution matters.
And just like Minervini, I’m not rigid with it.
Some trades might be 3 percent risk. Some 5 percent. Some 6 to 8 percent depending on the setup.
I’ll even go up to 10 percent and adjust position size, but I prefer tighter risk when the setup allows it.
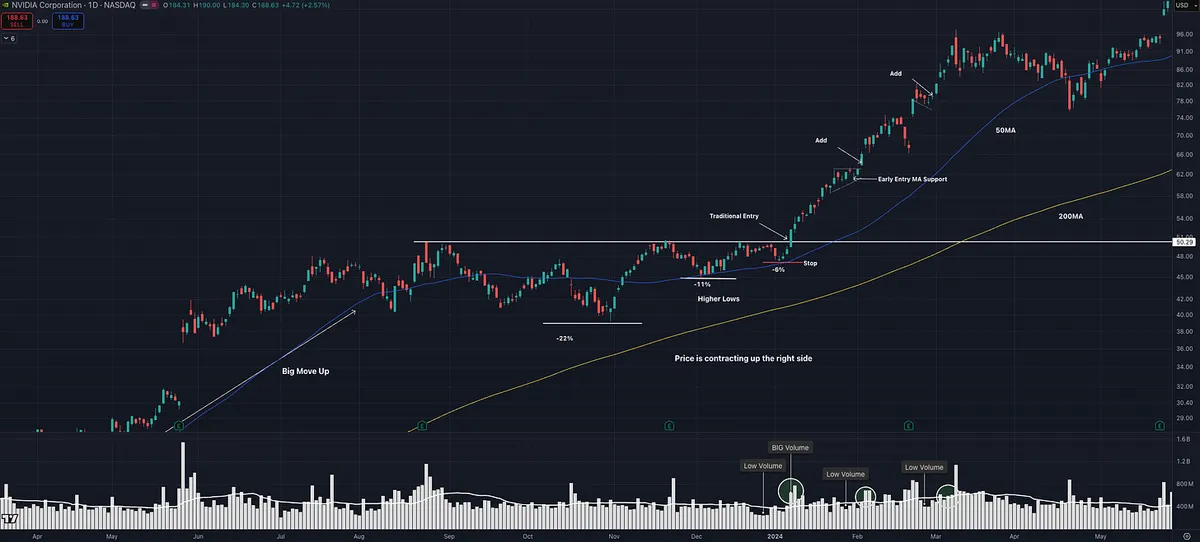
Another good example is NVDA in 2024. I had about 6 percent risk. Someone else could have taken the same trade and used the breakout day opening range low as a stop and risked closer to 1.82 percent and likely wouldn’t have been stopped out.
Like David Ryan often emphasizes, the best trades tend to be hard to buy, work right away, and don’t look back.
The principle stays the same.
Keep losses small. Don’t let one trade do real damage.
And at the end of the day, we all trade differently and that’s ok.
That’s what makes a market.
Different styles can still make money.