The Warnings Are There, but So Is the Strength
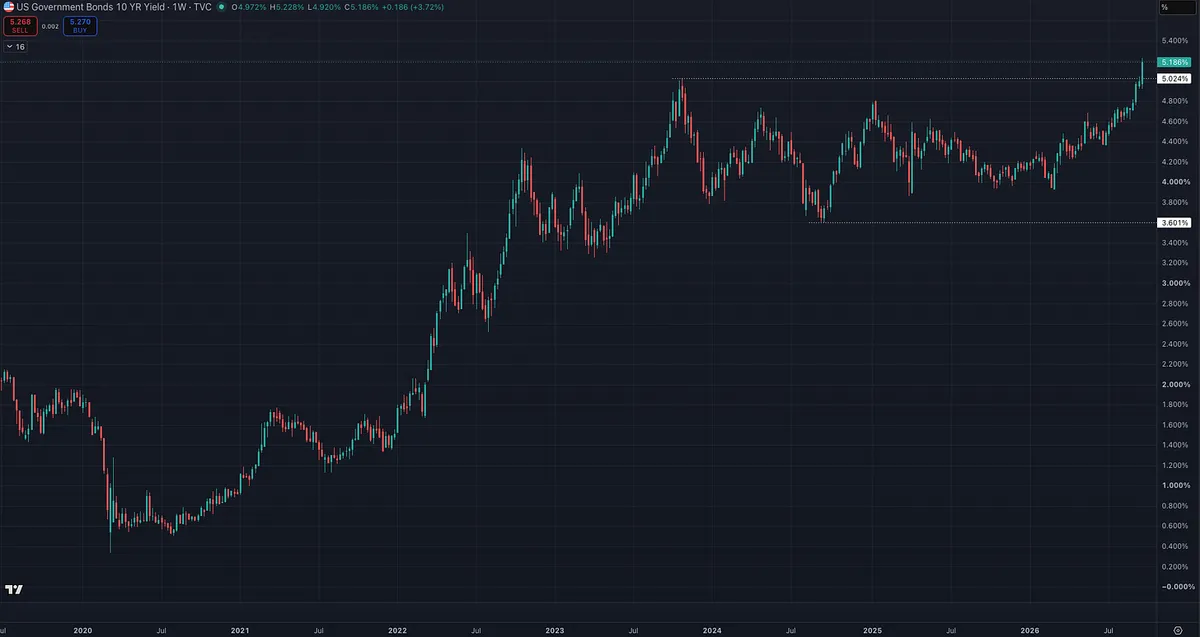
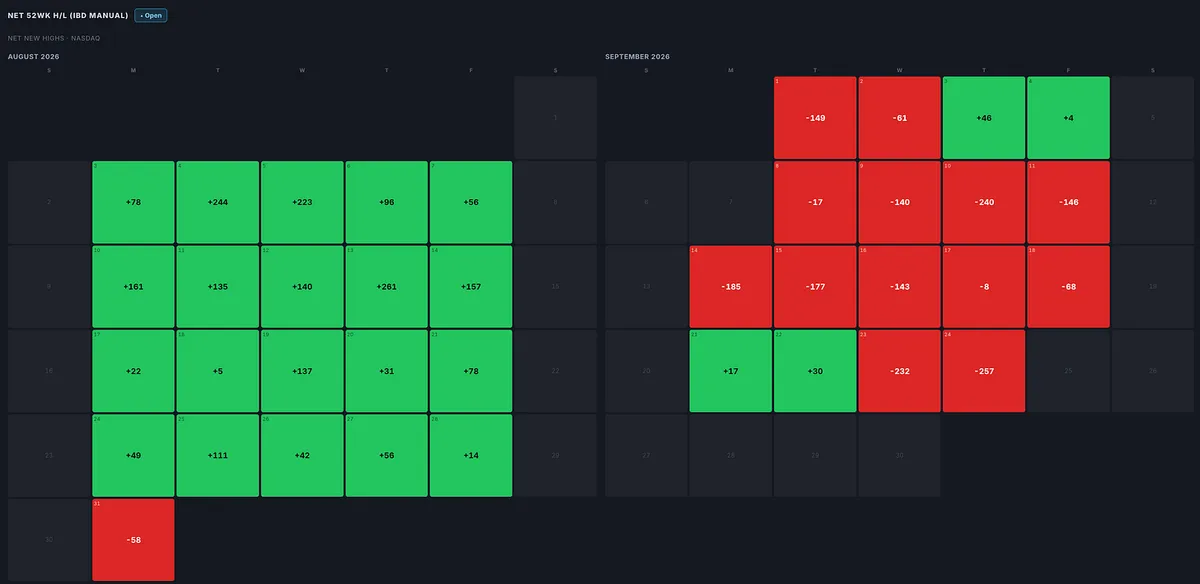
Net new lows and the percentage of stocks above key moving averages are showing some of the weakest readings I’ve seen since March. Stocks falling 4% have substantially outnumbered those rising 4%. Add a 10-year Treasury yield around 5.2%, and there are plenty of reasons to approach this market cautiously.
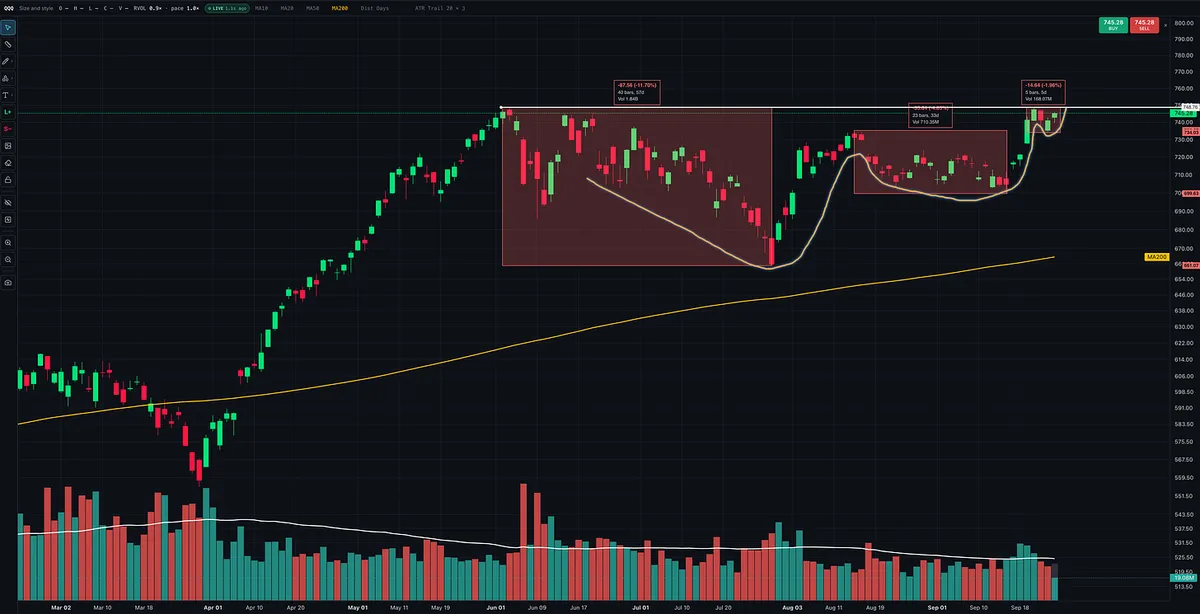
Yet look at QQQ and the Nasdaq Composite.
Both are sitting near their highs. On QQQ, successive pullbacks have narrowed from roughly 12% to 5% to 2%, creating VCP-like tightening up the right side of the chart. Meanwhile, leaders such as AMD continue to show strength.
The internal weakness is real, but so is the resilience in the leaders.
O’Neil explained that a market can continue advancing under the leadership of fewer, stronger stocks even as breadth deteriorates. Weinstein emphasized that weakening participation can warn of trouble before it becomes obvious in the averages. Those observations help explain why a constructive index chart and a weak broader market can exist at the same time.
The mistake would be letting either observation erase the other. QQQ holding near its highs doesn’t make the breadth deterioration irrelevant. Weak breadth doesn’t establish when the strongest stocks will stop advancing.
My approach is to respect the leading stocks and the indexes that reflect their strength. We are growth stock investors and momentum traders. We do not need every part of the market to be doing well to find opportunities in our stocks. Leadership is selective, and substantial gains can be concentrated in a relatively narrow group.
If stocks are setting up, breaking out, and following through, I will let those results help determine my exposure. The 10-year, the Dow, the Russell, and broader participation all provide context, but they do not automatically overrule constructive action in the stocks I trade. Price remains my most important indicator.
Will I remain aware of the poor breadth and rising yields? Absolutely.
But those warnings alone will not keep me on the sidelines while leading stocks continue to offer valid entries and reward them with progress. Successful breakouts and an expanding list of quality setups would support becoming more aggressive. Failed breakouts and deterioration in the leaders would support becoming more defensive.
Does participation improve around the leaders, or does the broader weakness eventually reach them?
That is what I’m watching, and I’ll adjust my exposure as the evidence develops.